First Home Buyer Home Loans
Andy made it straightforward and simple and represented us in a way that put our best foot forward.

Google Review
For the entire process Andy was a wealth of knowledge and provided excellent support, guidance and timely information.

Google Review
Top bloke, great service and locked in a great deal for us. Walked us through each step and had everything finalised really quickly.

Google Review
Andy made our refinancing and purchase of a new home seamless and within our guidlines.

Google Review
First Home Buyer Loan Structures We Arrange
Low Deposit Home Loans
Low Deposit Home Loans →
Guarantor Home Loans
A guarantor loan lets your parents or family help you buy a home by using their equity as security. Andy…
Guarantor Home Loans →
Self-Employed & Low Doc Home Loans
If you're self-employed, getting a home loan doesn't mean two years of perfect tax returns and full financials. Andy's been…
Self-Employed & Low Doc Home Loans →Access to every major lender—CBA, Westpac, NAB, Bankwest, Macquarie, and 30+ specialist lenders—so you’re not stuck with one bank’s first home buyer policy.










What Makes First Home Buyer Loans Different
A first home buyer loan isn’t a special product—it’s a standard owner-occupier home loan written for someone who’s never owned property in Australia before. What changes is eligibility for government support: the WA First Home Owner Grant ($10,000 for new builds under $750,000) and stamp duty concessions (full exemption on properties up to $430,000, partial concessions to $530,000 as of 2025).
Lenders treat first-timers cautiously because there’s no repayment history to verify—so the deposit size, your savings pattern, and stable employment become the approval anchors. If you’ve saved 10% genuine savings over 12+ months and held a job for two years, most mainstream lenders will approve you at 90% LVR (loan-to-value ratio) with lender’s mortgage insurance covering the gap.
The real variable is how you structure the deposit. Around 65% of Perth first home buyers I work with use a combination: part cash savings, part family gift or guarantor equity, part First Home Owner Grant. That’s not cutting corners—that’s using every legitimate lever to get in sooner without waiting for an unrealistic 20% cash pile.
Andy walks through this combination math in the first meeting. You’ll know exactly what deposit you need, what the grant covers, whether LMI applies, and what your repayments look like at current Mandurah interest rates—before you make an offer.
Most First-Timers Overestimate the Deposit They Actually Need
Most first home buyers in Perth assume they need a spotless 20% deposit saved before they can even start looking—but around 60% of the loans I write for first-timers involve 5–10% deposits, often with a family guarantor or the First Home Owner Grant filling the gap. The 20% figure avoids lender’s mortgage insurance, but LMI isn’t a deal-breaker—it’s a one-off premium (typically 1.5–3% of the loan amount) that lets you buy now instead of renting for another 3–5 years while property prices climb 4–6% annually.
Here’s the part people miss: waiting to save an extra $40,000 can cost you more than paying $8,000 in LMI today. If a $450,000 home in Secret Harbour appreciates to $480,000 in two years and you’re still renting at $480/week, you’ve spent $50,000 in rent and missed $30,000 in equity gain—far worse than the LMI hit.
The second myth: “I need perfect credit.” I’ve written loans for first-timers with a single $200 Telstra default from 2019, a casual employment contract, and a 7% deposit using Mum’s house as security. What matters more than a flawless Equifax score is a consistent savings pattern, stable income for 12+ months, and a sensible debt-to-income ratio. If you’re spending $600/week on Afterpay and car finance, that’s a bigger red flag than one old default.
Andy’s approach: structure the deposit to get you in sooner, explain the LMI cost vs the opportunity cost of waiting, and only recommend a guarantor when it genuinely improves your position—not because it’s easier for the lender.
How First Home Buyer Approval Works with Andy
Pre-Approval in 3–7 Days*
Full conditional approval with a certificate you can show real estate agents—not a soft online estimate. Most Perth lenders turn this around in 4 business days* when the file’s complete.
Line-by-Line Document Walkthroughs
Every loan contract explained in plain English before you sign—what the break costs mean, how offset works, when the fixed rate ends. No surprises at settlement.
Deposit Strategy Session
We map out your exact deposit scenario—cash, gift, grant, guarantor—and calculate LMI, stamp duty, and upfront costs so you know the real entry price.
Available When It Gets Urgent
Andy’s mobile: 0409 083 330. If something comes up at 7pm the night before settlement—a last-minute bank question, a valuation issue—you’re not waiting until Monday morning.
First Home Buyer Deposit Scenarios & What They Cost
Different deposit levels unlock different loan structures—and different upfront costs. Here’s what the math actually looks like for a $450,000 home in Mandurah or Baldivis in 2025:
| Deposit | LVR | LMI Cost (approx) | Stamp Duty | FHOG Eligible? | Total Upfront |
|---|---|---|---|---|---|
| 5% ($22,500) | 95% | $15,000–$18,000 | $0 (exempt) | Yes (new build) | ~$40,500 |
| 10% ($45,000) | 90% | $9,000–$12,000 | $0 (exempt) | Yes (new build) | ~$57,000 |
| 15% ($67,500) | 85% | $5,000–$7,000 | $0 (exempt) | Yes (new build) | ~$74,500 |
| 20% ($90,000) | 80% | $0 | $0 (exempt) | Yes (new build) | ~$90,000 |
| Family Guarantor (0% cash) | 105%+ | $0 | $0 (exempt) | Yes | Legal fees only (~$1,500) |
Stamp duty exemptions apply when the property is under $430,000; partial concessions extend to $530,000. The First Home Owner Grant ($10,000) is only available on new builds or substantially renovated homes under $750,000—it doesn’t apply to established homes.
Andy runs these scenarios in the first meeting so you can see which deposit path gets you in soonest without stretching repayments beyond 30% of your income.
How the First Home Buyer Loan Process Works
Initial Chat & Deposit Assessment
20-minute call or coffee in Mandurah. Andy asks about your income, savings, employment, debts, and what suburbs you’re looking at. You’ll leave knowing your realistic borrowing capacity and deposit options.
Pre-Approval Application
Andy lodges your file with the lender most likely to approve your scenario—not the one paying the highest commission. You’ll upload payslips, bank statements, ID, and any gift/guarantor letters. Conditional approval typically arrives in 3–7 days.
Property Search & Offer
Armed with pre-approval, you make offers knowing exactly what you can borrow. When an offer’s accepted, Andy orders the valuation and triggers formal approval while your conveyancer handles contracts.
Formal Approval & Document Signing
Bank valuation comes back, loan docs are issued, and Andy walks you through every schedule, condition, and clause line by line. You sign digitally; the lender releases funds to your solicitor.
Settlement & Handover
Settlement day: funds transfer, keys handed over. Andy stays in touch post-settlement for rate reviews, offset setup questions, and when you’re ready for the next property in 4–6 years.
What First Home Buyers Actually Pay in Upfront Costs
Beyond the deposit, expect $5,000–$12,000 in settlement costs depending on your loan size and structure. Conveyancing (solicitor/settlement agent) runs $1,200–$2,000. Building and pest inspections cost $400–$700 combined. Lender application fees are typically $0–$600 (some lenders waive them for first home buyers). If you’re paying LMI, that’s capitalised into the loan—you don’t hand over cash at settlement.
Stamp duty is the big variable: $0 if the property is under $430,000 (full exemption for first home buyers in WA), scaling up to around $8,500 for a $530,000 home under the partial concession, and $17,765 for a $600,000 home with no concession. Most Perth first-timers stay under $530,000 to preserve the concession.
Ongoing costs: loan repayments (principal + interest), council rates (~$1,400–$1,800/year in Mandurah), strata fees if applicable ($800–$2,500/year), and home insurance ($800–$1,500/year). Andy’s rule: if repayments plus rates plus insurance exceed 32% of your gross household income, the loan’s too tight for comfort.
Why First Home Buyers Choose Andy Over a Bank Branch
Experience Since 2000
Andy’s been broking in WA since two years after the industry started—he’s seen every market cycle, every lender policy shift, and every first-timer mistake Perth buyers make.
You Get His Mobile Number
Not a 1300 number, not a callback queue—Andy’s direct mobile. If settlement’s Friday and the bank emails a condition Wednesday night, you’re not stuck waiting.
Plain-English Walkthroughs
Every loan document explained line by line before you sign. No jargon, no rushing—you’ll understand what you’re committing to.
Structured Around You
Andy recommends the loan that suits your situation—not the one paying the most commission. Fixed vs variable, offset vs redraw, 30-year vs 25-year term—it’s your call, fully informed.
First Home Buyer Questions Perth Buyers Ask Andy
You can buy with as little as 5% genuine savings if you’re willing to pay lender’s mortgage insurance. Most Perth lenders will lend at 95% LVR (loan-to-value ratio) with LMI covering the risk. If you have a family member willing to guarantee the loan using equity in their home, you can borrow with 0% cash deposit—the guarantor’s equity substitutes for your deposit. The sweet spot for avoiding LMI entirely is 20%, but waiting that long often costs more in rent and missed property appreciation than the LMI premium itself. Andy runs the exact numbers in the first meeting so you can compare the cost of waiting vs the cost of buying sooner.
The WA First Home Owner Grant is $10,000 and applies only to new homes or substantially renovated homes valued under $750,000. You must be an Australian citizen or permanent resident, at least 18 years old, and you can’t have previously owned property in Australia. The grant doesn’t apply to established (existing) homes—so if you’re buying a 1990s brick-and-tile in Rockingham, you don’t get the grant, but you still get the stamp duty concession if the property is under $530,000. The grant is paid at settlement and can be used toward your deposit or to reduce the loan amount.
LMI is a one-off premium the lender charges when you borrow more than 80% of the property value—it protects them if you default, not you. The cost scales with your LVR: expect $5,000–$7,000 at 85% LVR, $9,000–$12,000 at 90% LVR, and $15,000–$18,000 at 95% LVR on a $450,000 home. You can capitalise LMI into the loan (borrow it) rather than paying cash upfront. The only ways to avoid LMI: put down 20% cash, use a family guarantor, or qualify for a professional-package loan (some lenders waive LMI for doctors, lawyers, accountants at 90% LVR). Andy’s view: if paying LMI gets you into the market two years sooner and property prices rise 5% annually, the LMI cost is cheaper than the opportunity cost of waiting.
A guarantor (usually Mum or Dad) uses equity in their own home as security so you can borrow 100%+ of the purchase price without a cash deposit. The guarantor doesn’t hand over money—they’re just offering their property as additional security. Most lenders limit the guarantee to 20% of your loan amount, and the guarantee drops off automatically once you’ve paid down the loan to 80% LVR (typically 2–5 years). The guarantor remains liable for that 20% portion if you default, so it’s a serious commitment. Andy structures these weekly for Perth families—common in Pinjarra, Baldivis, and Mandurah where parents want to help without gifting $50,000 cash. Full details: Guarantor Home Loans.
Yes, but lenders treat self-employed and casual income cautiously. For self-employed borrowers, most lenders want two years of tax returns showing consistent profit, plus your latest BAS statements and accountant’s declaration. If you’ve only been self-employed for 12 months or your income is variable, a low-doc lender can use 12 months of bank statements instead—slightly higher rate, but approvable. For casual employees, you need 12 months of payslips with the same employer and evidence your shifts are regular (not sporadic). If you’re a tradie on an ABN doing subbying work, that’s treated as self-employed. Andy works with self-employed first-timers every month—there’s always a structure that works*. More: Self-Employed & Low Doc Home Loans.
Variable rates move with the market—if the RBA cuts rates, your repayments drop; if they rise, repayments increase. You can make extra repayments without penalty and access offset or redraw facilities. Fixed rates lock your interest rate for 1–5 years, protecting you from rate rises but blocking you from extra repayments beyond $10,000–$30,000/year (depending on lender) and usually excluding offset accounts. As of mid-2025, Perth variable rates sit around 6.1–6.5% for owner-occupiers; 1-year fixed rates are 5.8–6.2%, 3-year fixed 5.9–6.4%. Andy’s recommendation for first-timers: split the loan 50/50 variable-fixed or go 70% variable/30% fixed so you have flexibility for extra repayments while hedging part of the rate risk. He doesn’t push one over the other—your cash flow and risk tolerance decide.
Pre-approval (conditional approval) is valid for 90–120 days depending on the lender. It’s a binding commitment from the bank that they’ll lend you the approved amount, subject to a satisfactory property valuation and no material change in your circumstances (e.g. you don’t quit your job or rack up $20,000 in new debt). Real estate agents in Perth and Mandurah treat pre-approval seriously—it proves you’re finance-ready and strengthens your offer. Once you find a property and make an offer, Andy orders the valuation and triggers formal approval, which typically takes another 5–10 business days. More detail: What Is Pre-Approval and How Long Does It Last?.
New builds qualify for the $10,000 First Home Owner Grant and full stamp duty exemption up to $750,000 purchase price in WA (as of 2025). They often have longer settlement periods (6–12 months if off-the-plan), lower maintenance in the first 5 years, and builder’s warranty. Established homes don’t qualify for the grant, but you can move in faster (4–6 week settlements), they’re often in more established suburbs closer to schools and shops, and you’re buying a known product (no construction delays). The financial trade-off: new builds let you borrow more (the grant becomes part of your deposit), but established homes in the same suburb are typically $20,000–$40,000 cheaper. Andy walks through both scenarios—if the grant and stamp duty saving total $15,000+ and you’re happy waiting for a new build in Baldivis or Secret Harbour, it’s often the smarter financial play.
An offset account is a transaction account linked to your home loan—every dollar in the offset reduces the loan balance you’re charged interest on. If you have a $400,000 loan at 6.2% and $20,000 sitting in offset, you only pay interest on $380,000, saving roughly $1,240/year. Offset accounts are standard on most variable-rate Perth home loans and cost nothing extra. Andy recommends them for every first-timer: dump your salary into offset, pay bills from there, and let the balance float—it’s free interest saving without locking money away. Fixed-rate loans usually don’t offer offset, which is why Andy often suggests a split loan if you want some fixed-rate certainty but still want offset flexibility. More: What Is an Offset Account vs a Redraw Facility?.
Yes, but existing debts reduce your borrowing capacity. Lenders use your debt-to-income ratio—total monthly debt repayments divided by gross monthly income—and most won’t lend if total debts (including the new home loan) exceed 6–7 times your annual income. A $15,000 car loan with $350/month repayments cuts your home loan capacity by roughly $70,000. Credit cards are treated harshly: lenders assume you’ll max out the limit, so a $10,000 card with a $0 balance still costs you ~$50,000 in borrowing power. Andy’s strategy: pay down or close high-limit credit cards 2–3 months before applying, and if a car loan has 12 months left, consider paying it out using savings or a small personal loan refinance to free up serviceability. He runs the numbers in the first meeting so you know whether to clear debt first or proceed as-is.
If you’ve offered $460,000 and the bank valuer assesses the property at $440,000, the lender will only lend against the $440,000 figure—so your loan-to-value ratio jumps. If you were borrowing 90% ($414,000), you’re now at 94% LVR and may need a bigger deposit or cop higher LMI. You have three options: renegotiate the price down (agents hate this but it happens), find extra deposit cash, or walk away if your contract has a finance clause. Andy orders the valuation as soon as your offer’s accepted and flags valuation risk upfront—if you’re buying in a thin market (rural fringe, unusual property type), he’ll warn you before you’re committed. Around 8–12% of Perth home loans hit a valuation shortfall; it’s fixable but stressful if you’re not prepared.
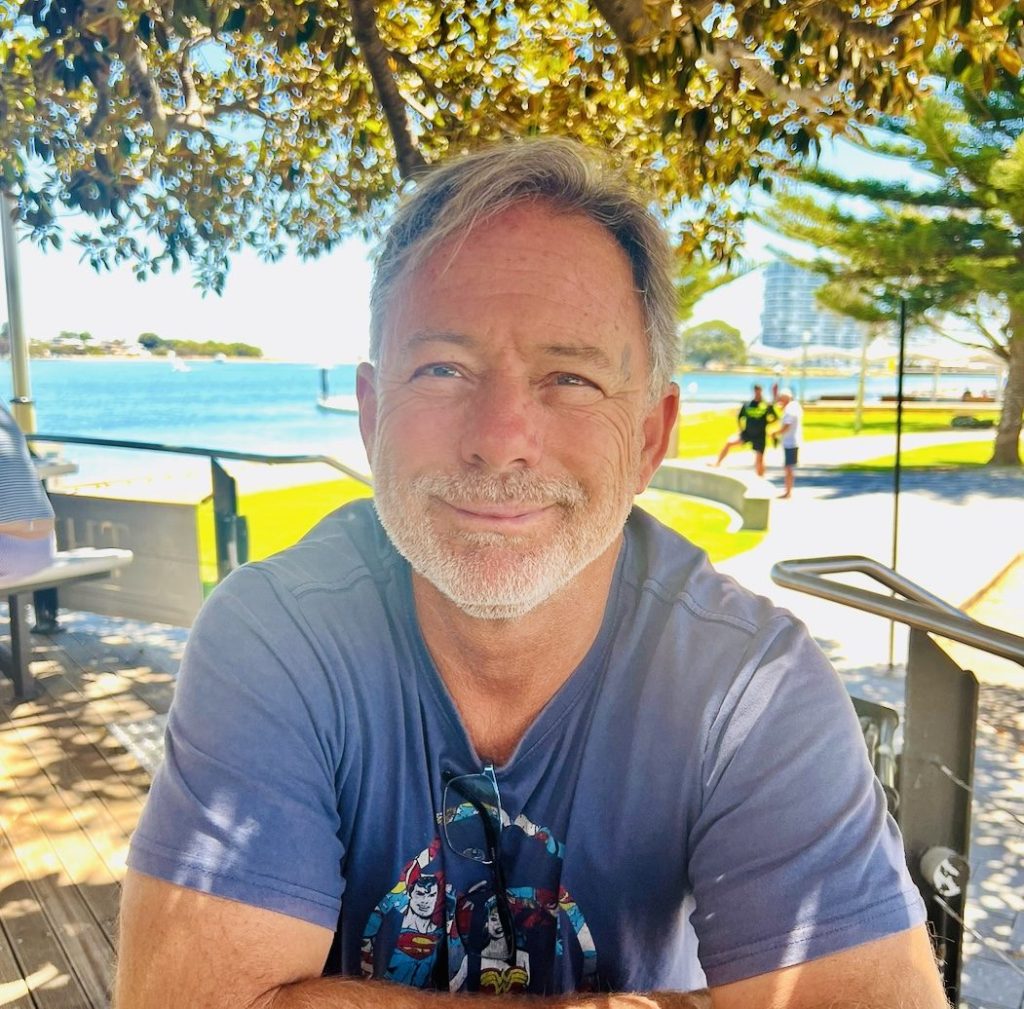
Andy's Been Helping Perth First Home Buyers Since 2000
Andy started broking in WA two years after the industry began—he’s seen every market cycle Perth’s thrown up, every lender policy shift, and every first-timer mistake buyers make. He’s not a franchise processor handing your file to a junior; you deal with Andy from the first deposit conversation through to settlement and beyond. Clients come back when they upgrade in five years, when they refinance, when they buy an investment property, because he keeps working for them after the loan settles.
Andy’s mobile: 0409 083 330. He picks up when something urgent comes up at night—a last-minute lender question, a valuation issue two days before settlement—not next business day. That’s the practical difference between a broker who’s been in the game since 2000 and one who started last year: experience you can’t shortcut, and availability when it actually matters.

Reviewed by
Credit Representative & Mortgage Broker
The information on this page has been reviewed for accuracy by Andy Iriks, a Credit Representative & Mortgage Broker at Wanna Finance. It is general information only.