Home Loan Refinancing
Wanna Finance helps homeowners in Mandurah & Perth refinance their home loan. Most homeowners stick with their original lender for years, paying loyalty tax while better rates sit one phone call away. Andy compares your current loan against 30+ lenders, handles the paperwork, and coordinates settlement—so you keep the savings, not the stress.
Andy made it straightforward and simple and represented us in a way that put our best foot forward.

Google Review
For the entire process Andy was a wealth of knowledge and provided excellent support, guidance and timely information.

Google Review
Top bloke, great service and locked in a great deal for us. Walked us through each step and had everything finalised really quickly.

Google Review
Andy made our refinancing and purchase of a new home seamless and within our guidlines.

Google Review
Let's Chat
Complete the form below and Andy will be in touch to discuss your finance needs.
Related Refinancing Services

Better Rate Refinancing
Better rate refinancing is used for securing lower interest rates to reduce repayment costs. Andy compares 30+ lenders to lock…
Better Rate Refinancing →
Cash-Out & Equity Release Refinancing
Cash-out refinancing lets you tap into your home's equity for renovations, investments, debt consolidation, or major purchases. Andy walks you…
Cash-Out & Equity Release Refinancing →
Debt Consolidation Refinancing
Turn six monthly payments into one—at half the interest rate. Andy shows when debt consolidation refinancing works and when it…
Debt Consolidation Refinancing →
Refinancing for Self-Employed Borrowers
Self-employed refinancing requires recent business financials and alternative income verification. Andy structures applications to maximise approval chances, working with specialist…
Refinancing for Self-Employed Borrowers →
What Is Home Loan Refinancing?
Home loan refinancing is the process of replacing your existing mortgage with a new loan from the same or different lender. The new loan pays out the old one, and you start making repayments under the new terms—ideally at a lower interest rate, with features that suit you better, or with access to equity you’ve built up. It sits at the heart of our refinancing service.
Most people refinance to reduce their interest rate. Mandurah homeowners who haven’t reviewed their loan in 3–5 years are typically sitting on rates 0.5%–0.9% higher than what’s available today. On a $450,000 loan, a 0.6% rate drop saves around $2,700 per year—$67,500 over a 25-year term.
Others refinance to access better loan features: an offset account that wasn’t available on their original loan, the ability to make extra repayments without penalty, or a redraw facility for emergencies. Some refinance to release equity for renovations, investment property deposits, or debt consolidation. And a growing number switch lenders simply because their current bank won’t negotiate or has let service standards slip.
The refinancing process requires a new loan application, a property valuation (usually organised and paid by the new lender), and settlement coordination between your old and new lender. When managed properly, the borrower’s involvement is minimal—Andy handles the lender liaison, document requests, and timing so nothing overlaps or delays your switch.
Refinancing isn’t always the right move. If you’re on a fixed rate with significant break costs, or if your property value has dropped and you no longer meet the new lender’s LVR thresholds, the numbers might not stack up. That’s why the first step is always a proper comparison: your current loan details, your goals, and what the market offers right now.
We query over 30 lenders to find an outcome that’s right for you










Why Mandurah Homeowners Refinance
Five practical reasons Mandurah homeowners make the switch—and why even a modest rate drop is worth a conversation.
Lower Interest Rates
A 0.5%–0.8% rate drop saves $2,000–$5,000 per year on a typical Mandurah mortgage. Even a small reduction compounds over the life of the loan.
Better Loan Features
Offset accounts, unlimited extra repayments, redraw facilities, and fee-free transaction accounts—features your original loan might not have offered.
Access Equity for Renovations or Investment
Tap into the equity you’ve built to fund a kitchen upgrade, buy an investment property, or consolidate high-interest debt into one manageable repayment.
Escape Poor Service
If your current lender won’t answer the phone, won’t negotiate your rate, or has changed your loan terms without notice, switching to a responsive lender is reason enough.
Consolidate Debt
Rolling credit cards, car loans, and personal loans into your home loan can cut your total interest bill and simplify repayments to one monthly payment.
What Refinancing Actually Costs
Refinancing isn't free, but the upfront costs are typically recovered within 8–14 months when the rate improvement is meaningful. Here's what you'll encounter:
Application fee: $0–$600 depending on the lender—many waive it during promotions. Property valuation: $0–$350, usually a free desktop valuation. Settlement fee: $150–$300 charged by your new lender. Discharge fee: $150–$400 charged by your current lender to release the mortgage—this is in your original contract and is non-negotiable. Government registration fees: around $200 in WA, collected by Landgate. Break costs only apply if you exit a fixed-rate loan early, ranging from $0 to $8,000+; Andy calculates these before you decide, so there are no surprises.
| Cost Item | Typical Range | Who Charges It | Notes |
|---|---|---|---|
| Application fee | $0–$600 | New lender | Often waived |
| Valuation | $0–$350 | New lender | Usually desktop (free) |
| Settlement fee | $150–$300 | New lender | One-off at settlement |
| Discharge fee | $150–$400 | Current lender | Non-negotiable |
| Registration fees | ~$200 | Landgate (WA Govt) | Statutory |
| Break costs (fixed) | $0–$8,000+ | Current lender | Calculated case-by-case |
| Total (variable loan) | $500–$1,500 | — | Recovered in 8–14 months on a meaningful rate drop |
If the numbers don't make sense, Andy will tell you to stay put. There's no point spending $1,200 to save $600 per year—but there's every reason to spend $800 to save $3,000 annually for the next decade.
How Refinancing Works with Andy
From first comparison to settlement, Andy manages the entire process so the only thing that changes for you is a lower repayment.
Review Your Current Loan
Andy pulls your current loan details—rate, features, outstanding balance, fixed-rate expiry if applicable—and compares them against the best available products across 40+ lenders.
Shortlist the Right Options
You get 2–3 shortlisted loan options with clear rate comparisons, feature breakdowns, and cost-vs-saving calculations. No jargon, no sales pressure—just the numbers you need to decide.
Lodge the Application
Andy submits your application to the chosen lender, provides any supporting documents they request, and manages follow-ups. You’re kept in the loop without chasing updates yourself.
Property Valuation
The new lender arranges a valuation to confirm your property’s current market value. In most cases, this is a desktop valuation at no cost to you. If a physical inspection is needed, Andy coordinates the timing.
Formal Approval
Once the lender approves your loan, you receive formal loan documents to review and sign. Andy walks you through each clause so you know what you’re committing to before you sign.
Settlement
Your new lender pays out your old loan on settlement day. The discharge is processed, and your repayments switch to the new loan. The entire coordination happens behind the scenes—you just start paying the new rate.
What People Get Wrong About Refinancing
Most Mandurah homeowners I speak to assume refinancing is a big production—weeks of forms, valuations that cost hundreds, and lenders demanding fresh financials. In reality, 70% of the refinances I arrange settle without the borrower stepping into a bank, the valuation is covered by the lender, and the entire process takes 3–4 weeks when your paperwork is straightforward.
The other assumption: you need a 20% deposit or you can’t refinance. Not true. If your property has appreciated and your LVR now sits below 90%, plenty of lenders will refinance you—even if you originally borrowed at 95% LVR. Mandurah’s median house price rose 18% between 2020 and 2023; that appreciation alone has pushed thousands of borrowers into better LVR brackets without them realising it.
The part people underestimate: the loyalty tax compounds every year you wait. A $450,000 loan at 5.8% costs $2,610 per month. The same loan at 5.2% costs $2,485 per month—a $125 monthly difference, or $1,500 per year. Over five years of inaction, that’s $7,500 handed to your current lender for no reason other than inertia.
If you’re self-employed, refinancing isn’t harder—it just requires the right lender and a broker who knows which ones accept single-year financials or alternative income verification. I’ve refinanced tradies, sole directors, and PAYG contractors dozens of times; the trick is matching your income documentation to the lender’s appetite, not trying to force your situation into a policy box it won’t fit.
Refinancing Timeline: What to Expect
How long refinancing takes depends on your loan complexity, your documentation readiness, and the lender’s current workload. Here’s what to expect across three common scenarios:
| Scenario | Typical Timeline | Key Steps |
|---|---|---|
| Straightforward PAYG, standard loan | 3–4 weeks | Application lodged → valuation (2–5 days) → conditional approval (5–7 days) → formal approval (3–5 days) → settlement (7–10 days) |
| Self-employed borrower | 4–6 weeks | Application lodged → accountant statements requested → valuation → conditional approval (7–10 days) → formal approval → settlement |
| Equity release for renovation or investment | 5–7 weeks | Application lodged → valuation (may require physical inspection) → builder quotes / investment contract reviewed → conditional approval (10–14 days) → formal approval → settlement |
The critical path: most delays happen at the valuation or conditional approval stage. If the valuer can’t access your property, or the lender requests payslips or bank statements you don’t have on hand, the clock resets—so Andy front-loads the document gathering before lodging.
Fixed-rate expiry refinancing: if your fixed term expires in 2–3 months, start now. You want formal approval locked in before your loan reverts to the lender’s standard variable rate, which is often 1%–2% higher than competitive variable rates.
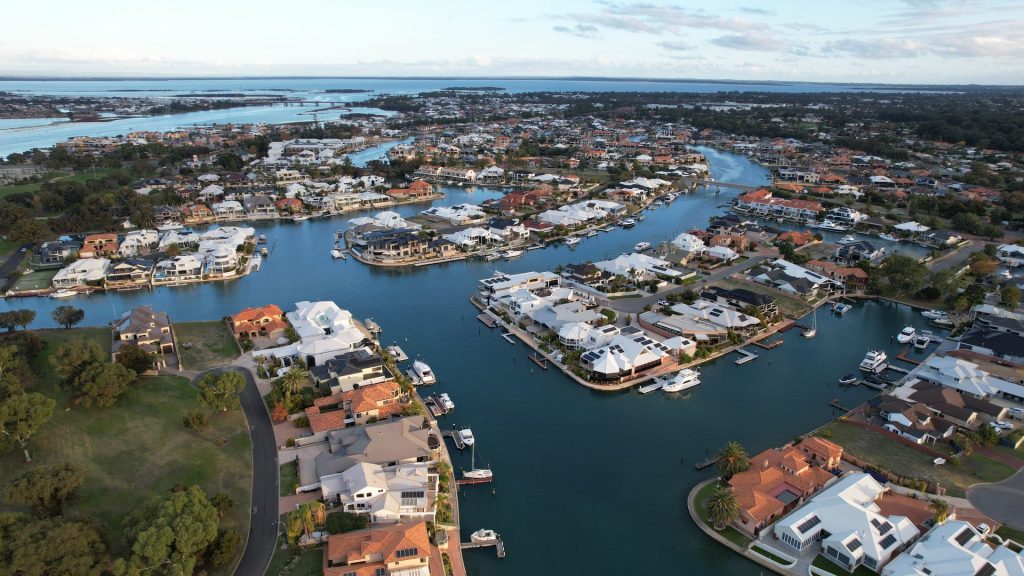
How Andy Helped a Baldivis Family Save $3,200 Per Year
A young family in Baldivis came to Andy in early 2023 with a $520,000 home loan they’d taken out in 2019 at 4.9%. Their lender had bumped the rate to 6.2% over successive RBA hikes, and they were paying $3,685 per month. They assumed switching lenders would be a hassle—new paperwork, another valuation, weeks of back-and-forth—and kept putting it off.
Andy ran the numbers: their property had appreciated 12% since purchase, dropping their LVR from 90% to 78%, and they now qualified for premium-tier pricing. He shortlisted three lenders offering 5.49%–5.69% with offset accounts and unlimited extra repayments—features their original loan didn’t have. They chose a 5.54% product; the new repayment landed at $3,420 per month, saving them $265 monthly or $3,180 per year.
The refinance cost $950 in total (application fee waived, $200 discharge, $150 settlement, $200 government fees, $400 valuation). They recovered the cost in four months and have since banked the ongoing savings into their offset account, which is now reducing their interest bill further. The entire process took three weeks; they signed documents at home, the valuation was a kerb-side desktop at no cost to them, and settlement happened without them needing to attend the bank.
The difference wasn’t the rate alone—it was having someone who knew which lenders would accept their slightly irregular PAYG structure (one partner was on a 12-month contract) and who could submit the application correctly the first time. No declined applications, no wasted credit enquiries, no surprises at settlement.
Common Refinancing Questions
Savings depend on your current rate, your loan balance, and the new rate you qualify for. A 0.5% rate drop on a $450,000 loan saves ~$2,250 per year; a 0.8% drop saves ~$3,600 annually. Over a 25-year term, that’s $56,000–$90,000 in total interest saved. Andy runs a savings calculation using your actual loan details before you commit to anything.
The best time is when the rate saving or feature improvement outweighs the refinancing costs—typically when you can drop your rate by 0.4% or more, or when your current lender won’t provide features (offset, redraw, extra repayments) you need. If your fixed rate is expiring in 2–3 months, start now so approval is locked before you revert to a higher variable rate. Most Mandurah homeowners should review their loan every 2–3 years; rates and lender policies shift faster than people realise.
Yes—self-employed borrowers refinance all the time. You’ll need 1–2 years of tax returns, recent BAS statements, and a profit-and-loss or accountant’s letter depending on the lender. Some lenders accept single-year financials for established businesses; others want two full years. Andy knows which lenders are flexible with sole traders, contractors, and directors, and which ones will ask for three years of perfect paperwork. The key is matching your income documentation to the lender’s criteria before you apply.
No—you need 20% equity in your property (80% LVR or lower) to avoid Lenders Mortgage Insurance on the refinance, but you don’t need cash. If your property has appreciated or you’ve paid down your loan, you may already be below 80% LVR without realising it. Mandurah’s median house price growth over the last few years has pushed many borrowers into better LVR brackets automatically. Andy checks your current LVR as part of the comparison—if you’re above 80% but below 90%, refinancing is still possible; you’ll just pay LMI on the new loan if the lender requires it.
For PAYG employees: last two payslips, last two years of tax returns (or ATO notice of assessment), 3–6 months of bank statements, and your current loan statement. For self-employed: last two years of tax returns, recent BAS statements or profit-and-loss, business bank statements, and your current loan statement. For equity release refinances, you’ll also need builder quotes, renovation plans, or the investment property contract if you’re using the funds for a purchase. Andy provides a checklist tailored to your situation so you’re not hunting for documents twice.
3–4 weeks for straightforward loans (PAYG income, standard property, no complications). 4–6 weeks for self-employed borrowers or loans with equity release components. 5–7 weeks if a physical valuation is required or if the lender requests additional documentation mid-application. The timeline depends on how quickly you provide documents, how busy the lender’s credit team is, and whether your property valuation comes back at the expected value. Andy manages the process and keeps you updated at every stage so there are no surprises.
Refinancing generates a credit enquiry, which appears on your credit file and may lower your score by 5–10 points temporarily. The impact is minimal and recovers within a few months as long as you continue making repayments on time. Multiple refinance applications within a short window (for example, applying directly to 4 lenders in one month) will hurt your score more than one broker-submitted application, because each lender enquiry is logged separately. Andy submits one application to the best-fit lender, so your credit file shows one enquiry, not four.
It depends on your current LVR. If your property value has dropped but you’ve paid down enough of the loan to keep your LVR below 80%, most lenders will still refinance you. If the drop pushes you above 90% LVR, your refinancing options narrow significantly—some lenders won’t touch high-LVR refinances, and those that do will charge LMI. Andy checks your property’s current estimated value (using recent sales in your street and suburb) before lodging an application, so you know where you stand before the formal valuation.
Your existing offset account closes when you discharge your old loan, and any funds in it are returned to you (or transferred to your new loan’s offset if the new lender offers one). If your new loan includes an offset account, you can deposit the funds there immediately and continue offsetting interest. If your new loan doesn’t have an offset, those funds sit in a regular transaction account and don’t reduce your interest. Andy highlights offset availability during the lender comparison so you’re not surprised after settlement.
Minor credit issues (one missed payment 18+ months ago, a small default that’s been paid) won’t necessarily disqualify you, but they’ll limit your lender options and may result in a higher rate. Recent defaults, multiple missed payments, or discharged bankruptcies will make mainstream refinancing difficult; you’ll need a specialist non-conforming lender, and rates will be higher. Andy assesses your credit file before applying and recommends whether to proceed now, wait 6–12 months for the issues to age off, or go straight to a specialist lender if time-sensitive.
You can refinance directly with a lender, but you’ll only see that lender’s rates and features—and you’ll handle all the paperwork, liaison, and settlement coordination yourself. A broker compares 40+ lenders in one conversation, negotiates on your behalf, and manages the process so you’re not chasing updates or translating policy documents at 9pm. Andy’s service is free to you (lenders pay the broker fee), and his clients typically save more on the rate negotiation alone than they’d achieve going direct. The value isn’t just the rate—it’s the time saved, the features explained, and the certainty that the loan suits your situation before you sign.

Reviewed by
Credit Representative & Mortgage Broker
The information on this page has been reviewed for accuracy by Andy Iriks, a Credit Representative & Mortgage Broker at Wanna Finance. It is general information only.